How to calculate the payback period for packaging automation systems
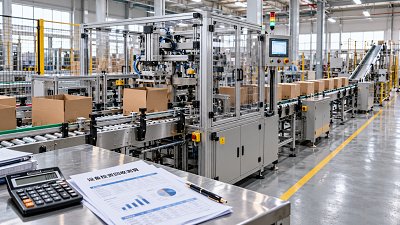
The payback period for packaging automation is the time required for cumulative incremental cash savings to recover the project’s initial cash investment. For packaging automation equipment systems with stable annual savings, divide total installed cost by annual net cash savings. When installation payments, production ramp-up, or seasonal demand affect the result, calculate cash flow month by month and identify when the cumulative balance first becomes positive.
A defensible calculation starts with a realistic alternative: continuing with existing equipment, replacing an aging machine, or expanding through additional manual capacity. The investment must recover its cost through measurable changes against that alternative. Rated throughput, reduced staffing requirements, and lower scrap become financial benefits only when the operating conditions behind them hold.
Establish the investment that must be recovered
The equipment quotation rarely represents the full project cost. A folder-gluer, case packer, or palletizing cell also needs compatible material handling, controls integration, and a production-ready installation. Excluding these items shortens the apparent payback while leaving the actual cash requirement understated.
Build the investment estimate around the complete operating boundary, from incoming blanks or products to the accepted finished package. Include upstream and downstream modifications where the proposed system requires them.
Record recoverable taxes according to their expected payment and recovery dates. Include nonrecoverable taxes in project cost. Deduct proceeds from existing equipment only when disposal is credible, allowing for removal and transaction costs. An assumed resale value without a realistic sale route should remain outside the base case.
Installation downtime also requires careful treatment. Lost production creates a financial loss when it causes missed contribution or additional recovery costs. If inventory covers shipments without extra spending, valuing every stopped production hour as lost sales overstates the transition cost.
Translate operating improvements into cash
Use the same production volume, product mix, and quality requirements when comparing the existing process with automation. Otherwise, differences in demand or packaging specifications become mixed with equipment benefits. Build the baseline from production records, payroll, material consumption, maintenance spending, and shipment performance across a representative operating period.
Labor savings require an identifiable spending change
Calculate avoidable labor cost from the hours that will actually disappear from payroll, agency invoices, or overtime. Include employer costs that change with those hours. A lower theoretical staffing requirement does not automatically produce a cash saving.
Redeploying employees to another operation creates a financial benefit when it avoids a planned hire, reduces paid overtime, or supports additional profitable shipments. Without one of those outcomes, show the released hours separately as available capacity.
Account for the work that remains around the automated process. Blank loading, adhesive replenishment, rejected-pack handling, changeovers, cleaning, and fault recovery still consume time. An automatic folder-gluer running one repeat carton format has a different labor profile from the same machine handling frequent changes in board thickness, dimensions, and folding configuration.
Material savings need a consistent denominator
Measure packaging material consumption per accepted, saleable unit. This captures startup waste, damaged blanks, rejected packs, and material consumed in rework. Comparing scrap percentages alone becomes misleading when the existing and proposed processes classify rejects differently.
For paper-based packaging, board stiffness, warp, scoring quality, and adhesive behavior affect feeding and bonding performance. Savings demonstrated with selected blanks require validation against the actual material specification and expected variation. Reduced adhesive application counts as a benefit only while bond integrity remains acceptable.
Value avoided waste at the cash cost actually saved, net of any scrap recovery income lost. Include downstream materials or product contents only when the defect genuinely causes their disposal. Do not count the same rejected pack again under separate quality and material-saving headings.
Additional output earns value through shipments
Higher machine speed creates cash when there is demand for additional output and the rest of the operation can process it. A faster packing cell adds little shipment capacity if carton supply, curing time, pallet movement, or warehouse dispatch remains the constraint.
Calculate the contribution from incremental saleable shipments after deducting their variable cash costs. Revenue alone overstates the benefit. Extra board, adhesive, energy, freight, labor, and selling costs belong in the calculation wherever they increase with those shipments.
There is also a useful alternative to claiming new sales: avoided outsourcing or avoided overtime. Select the outcome supported by the production plan. Counting additional sales and avoided external production for the same units duplicates the benefit.
Subtract the new operating costs before calculating payback
Automation changes the cost structure. Maintenance contracts, replacement belts, vacuum components, sensors, software subscriptions, and specialist service visits can offset part of the gross savings. Include incremental electricity and compressed-air consumption, using operating hours and duty cycles that match the production plan.
Compare the proposed system with the spending required to keep the current process running. Existing maintenance costs that genuinely disappear are savings; maintenance costs that continue elsewhere in the line remain in the baseline. For an aging machine, support avoided repair expenditure with service history and a credible replacement or repair plan.
Recurring cash benefits should also reflect ongoing training, format tooling replacement, and periodic service work. Large payments do not become irrelevant because they fall outside the first year. Place them in the period when payment is expected.
Annual net cash savings = avoidable operating costs + incremental sales contribution − additional operating cash costs.
Depreciation is excluded from a pre-tax cash-payback calculation because it is a noncash expense. An after-tax model must account for applicable tax effects, including depreciation-related tax savings. Keep pre-tax and after-tax assumptions consistent throughout the investment and operating cash flows.
Use a monthly model when the savings do not start immediately
Simple payback in years = initial net investment ÷ steady annual net cash savings.
This shortcut is useful when the investment occurs upfront and savings begin promptly at a stable rate. It becomes optimistic when commissioning takes time, staffing reductions are delayed, or customer qualification limits shipments after startup.
For a monthly model, enter actual expected payment dates for deposits, delivery milestones, installation, and acceptance. Add operating benefits and costs in the months when they affect cash. Cumulative project cash flow equals all project cash inflows minus all project cash outflows through each month.
The payback point is the first month in which that cumulative amount reaches zero. If interpolation within a month is useful, divide the unrecovered balance at the preceding month-end by the following month’s positive net cash flow. This assumes cash generation is reasonably even within that month.
Define the starting point explicitly. Measuring from the first project payment captures the full capital commitment period; measuring from production acceptance excludes the earlier cash exposure. Both descriptions appear in investment discussions, so an unlabeled payback figure creates avoidable ambiguity.
Ramp-up assumptions should connect to specific production events: approved formats, stable feeding, acceptable glue bonds, trained shift coverage, and completed upstream or downstream interfaces. Avoid applying one broad utilization discount when these events have different schedules. Seasonal packaging demand also belongs in the monthly forecast rather than being spread evenly across the year.
Test the assumptions that can change the decision
The strongest sensitivity analysis focuses on uncertain variables with a clear effect on cash. For packaging automation, these frequently include avoidable paid hours, usable production time, material yield, and the date at which stable operation begins.
Derive saleable capacity from scheduled operating time, changeover and stoppage losses, demonstrated running speed, and accepted output. Keep the definitions consistent. If a measured effective production rate already includes stoppages and rejects, applying additional availability and quality reductions counts those losses twice.
Use representative product families when testing equipment performance. Long runs of uniform corrugated cases will not reveal the same constraints as short runs involving multiple carton sizes, sensitive print finishes, or difficult folding sequences. A volume-weighted mix gives a more useful capacity estimate than the fastest demonstration format.
- Delayed staffing savings: move the payroll reduction to the date when vacancies, contract changes, or shift restructuring make it achievable.
- A slower ramp should reduce early savings and include the extra trial materials, support, and temporary production arrangements associated with that delay.
- Lower demand: remove unsupported incremental shipments while retaining costs that continue at the lower volume.
- For material variability, use trial evidence to assess whether feeding losses, adhesive consumption, or reject rates change enough to affect the investment case.
Test related assumptions together. Lower demand can reduce both throughput benefits and labor savings if the remaining production still requires the same shift coverage. Separate sensitivity changes would miss that interaction.
A useful break-even calculation works backward from the permitted investment horizon: divide the recoverable investment by the required number of years to find the annual net cash savings needed under a steady-state assumption. Compare that requirement with evidenced savings. Use the monthly model to confirm the result where ramp-up or payment timing is material.
Make the approval figure traceable to operating evidence
Each material benefit needs a source, a calculation, and a condition for realization. Labor savings should reconcile with staffing schedules and paid hours. Material savings should link to accepted-output records or representative trials. Throughput benefits need an identified production constraint, sufficient downstream capacity, and demand that supports additional shipments.
Supplier acceptance criteria should cover the conditions used in the financial model: specified materials, representative formats, sustained saleable output, changeover performance, and the staffing needed to achieve those results. A short speed demonstration offers limited evidence for a forecast built around full-shift operation.
Payback measures capital recovery speed and ignores cash generated after recovery. Compare it with net present value over a consistent evaluation period when alternatives have different service lives, maintenance profiles, or later cash benefits. If discounted payback is reported, identify the discount rate and keep it distinct from simple payback. Where cumulative cash flow never recovers the investment within the modeled period, report that result directly rather than extending steady savings beyond supported operating assumptions.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Got questions about the latest insights discussed here, or seeking customized strategic advice for your business? Drop us a line below, and let the think-tank experts at IPPS help you out.
“We respect your privacy. Your information is strictly confidential.”
Recommended News