How to calculate payback on industrial digital printing equipment
Calculate payback on industrial digital printing equipment by dividing the total installed investment by annual net incremental cash flow. That gives a useful first estimate when annual cash flow is stable. When installation, qualification, and order conversion create a gradual production ramp, calculate payback from cumulative monthly cash flow instead. The recovery point is the month when the investment and all subsequent project cash outflows have been covered by cash generated or saved.
A credible calculation starts with the work the press will actually produce, the costs that will disappear, and the additional spending required to deliver saleable output. Headline print speed and projected revenue alone cannot establish the return.
Define the investment and the alternative being compared
Payback measures the difference between proceeding with the investment and continuing with a defined alternative. That alternative could be keeping an existing press, outsourcing selected jobs, replacing an obsolete machine, or buying a different production system. Use the same order volume, quality requirements, and delivery obligations on both sides of the comparison.
If an existing press can continue operating, its historical purchase price is a sunk cost. Relevant future costs include maintenance, consumables, labor that changes, and any replacement spending the digital investment would avoid. If replacement is unavoidable, compare the digital project against the credible replacement option. Comparing a new press with an unrealistic “spend nothing indefinitely” baseline distorts the result.
The investment boundary must cover everything needed to reach commercial production:
- Equipment and installation: the press, delivery, rigging, commissioning, and required electrical, compressed-air, extraction, or cooling work.
- Workflow software, raster image processing, color management, inspection systems, and integration with estimating or production scheduling.
- Application-specific additions. Priming, drying, curing, substrate handling, and finishing capacity belong in the project when the intended jobs require them.
- Training, qualification materials, startup waste, and essential initial spares, with payment dates recorded separately from recurring operating expenses.
Include additional working capital when the project increases inventories or receivables after allowing for supplier payment terms. Subtract confirmed disposal proceeds from replaced equipment when they are received. Recoverable taxes should follow their actual payment and recovery timing; nonrecoverable charges remain project costs.
Build cash flow from saleable work
Annual net incremental cash flow = cash savings on existing work + cash contribution from additional work − additional fixed cash costs − incremental cash taxes − increases in working capital.
This is a cash calculation. Depreciation affects accounting profit and potentially cash taxes, but it is not itself a cash payment. Allocated overhead also requires care: moving a share of building rent onto the new press does not create an additional project outflow if total rent remains unchanged.
Divide the expected workload into meaningful job groups, such as short-run cartons, variable-data labels, or corrugated display sheets. Each group should have its own substrate, coverage, setup frequency, finishing route, and selling assumptions. A single average cost per sheet hides differences that can determine whether the investment pays back.
Keep benefits from existing work separate from benefits requiring new demand. This makes it possible to see whether committed production supports the investment or whether recovery depends on winning additional business.
Separate contribution from revenue
For new orders, deduct substrate, ink, coatings, production labor, finishing, freight, selling commissions, and other incremental costs from sales. The remainder contributes toward the investment and additional fixed expenses. Counting the full selling price as a payback benefit substantially overstates cash generation.
Transferred work follows a different calculation. If the same order was already being sold, its revenue is not new. The benefit is the difference between the old route’s avoidable costs and the digital route’s cash costs. Count an additional price premium only when there is evidence that the order will retain that premium.
Labor savings require an identifiable cash effect. Reduced overtime, avoided agency labor, or an avoided planned hire can produce cash savings. Redeploying existing staff creates available capacity, but payroll savings arise only when payroll expenditure changes. If redeployed hours support extra production, recognize the resulting contribution without also claiming the same hours as a payroll reduction.
Translate rated speed into usable production
Rated speed describes a particular operating condition. The payback model needs accepted output under the intended combination of substrate, coverage, resolution, drying, and finishing requirements. High coverage or a difficult substrate can change operating speed, consumable use, and reject rates together.
Start with scheduled production hours, then deduct planned maintenance, cleaning, job changes, calibration, and expected unplanned stoppages. Apply the demonstrated running speed and accepted yield to the remaining time. Keep these deductions separate so that downtime and rejects are not counted twice through overlapping efficiency factors.
Saleable capacity = scheduled hours × availability × demonstrated running rate × accepted yield.
Use this result as a capacity ceiling. Forecast sales volume must also fit the available order book and downstream capacity. A press with spare hours does not generate revenue unless suitable jobs are available, and printed sheets do not become saleable cartons while waiting indefinitely for die-cutting or folding-gluing.
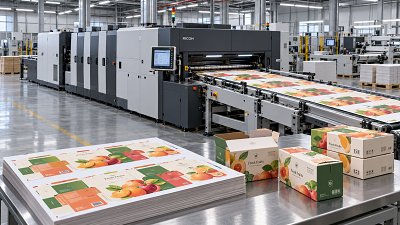
Production trials should follow representative files through the complete route. Record accepted output, elapsed time, ink consumption, cleaning consumption, substrate losses, and finishing results. A press-side inspection alone can miss cracking at creases, inadequate adhesion, rub damage, or dimensional problems discovered later.
Define yield at the point where the product is accepted for shipment. Otherwise, the model can recognize contribution from sheets that consume printing resources but fail during conversion.
Make consumable and service costs match the application
Ink estimates deserve particular scrutiny because coverage, print mode, and maintenance behavior affect consumption. File-based estimates are useful for comparing artwork, but the operating budget must also include ink used for purging, cleaning, startup, and rejected output. Confirm whether quoted consumption represents ink placed on the substrate or total ink drawn from the supply.
White ink, primers, varnishes, and pretreatment change the cost structure where applications require them. Drying or curing energy should reflect the intended operating mode. Substrate purchasing also matters: a material that runs reliably on an existing process might require treatment or a different grade on the proposed digital system.
Service agreements need the same precision. Establish which parts, printheads, labor, travel, and scheduled interventions are included. If printheads are excluded, model replacement spending using documented assumptions appropriate to the application. Avoid treating the service fee as complete maintenance coverage when exclusions create additional cash obligations.
Minimum usage charges and recurring software fees can make unit costs rise sharply at low utilization. Model those obligations as fixed or minimum cash payments where appropriate. Dividing every cost by the supplier’s projected annual volume conceals the effect of an underfilled schedule.
Use monthly cash flow through startup and recovery
The simple formula, investment divided by stable annual cash flow, assumes the recurring benefit is available consistently. Installation delays, customer qualification, and gradual job transfer break that assumption. A monthly model captures deposits, installation payments, commissioning expenses, and the timing of the first commercial receipts.
Record each month’s project cash inflows and outflows, then maintain a running cumulative balance. Payback occurs when that balance reaches zero from below. Where a whole-month result is too coarse, interpolation within the recovery month is reasonable if cash generation is sufficiently even.
Separate three startup constraints: equipment availability, application approval, and order migration. Mechanical completion does not establish that every substrate and artwork combination is commercially qualified. Likewise, successful qualification does not guarantee that existing customer orders can immediately move from their previous production route.
Customer payment terms can delay cash recovery after production becomes profitable. Avoid deducting a receivables increase separately if the model already schedules customer receipts by their actual collection dates. The same principle applies to inventory purchases and supplier payments: choose a consistent cash-flow method.
For an unlevered project comparison, exclude loan proceeds, principal repayments, and interest, and apply the chosen investment discount rate when calculating net present value. A separate equity cash-flow model can show the effect of financing. Combining financed equipment payments with the full purchase outlay would double-count the investment.
Find the assumptions that change the approval outcome
A downside case should describe a coherent operating situation. Lower order volume, for example, reduces contribution while service minimums and software subscriptions remain payable. Slower qualification delays receipts and can extend outsourced production costs. Higher coverage raises ink consumption and can also constrain drying speed.
Test these relationships together where they share a cause. Moving every input independently produces scenarios that look precise but do not represent an achievable production schedule.
A useful reverse calculation starts with the required recovery period:
Required annual net cash flow = total installed investment ÷ target payback period.
For a stable operating year, add incremental annual fixed cash costs to that required cash flow, then divide by the contribution per saleable unit. The result estimates the annual volume needed to meet the target, before adjustments for ramp-up, taxes, and working capital. A monthly model should resolve those adjustments.
Compare that volume with both demonstrated capacity and supportable demand. If it exceeds either, the target payback is unsupported under the current assumptions. This calculation also exposes whether a modest change in price, ink consumption, or utilization would move recovery beyond the acceptable period.
Connect the purchase terms to the model’s evidence
The final approval case should retain a traceable source for each material assumption: a quotation, production record, trial result, contract provision, or documented demand estimate. Supplier projections can remain in the model, but their effect should be visible separately from measured performance.
Acceptance terms should describe the production conditions used in the calculation, including substrate, artwork coverage, quality requirements, sustained output, and waste measurement. Training, service response, and installation responsibilities also need defined boundaries where they affect startup timing or operating costs.
Payback alone does not measure the value created after recovery. Net present value provides a companion assessment of cash flows across the planned ownership period, including major maintenance and supportable residual value. An attractive recovery date is more persuasive when it survives realistic production conditions and remains consistent with a positive lifecycle investment case.
Industry Briefing
Get the top 5 industry headlines delivered to your inbox every morning.
Got questions about the latest insights discussed here, or seeking customized strategic advice for your business? Drop us a line below, and let the think-tank experts at IPPS help you out.
“We respect your privacy. Your information is strictly confidential.”
Recommended News